GOOD MORNING!
FOREX
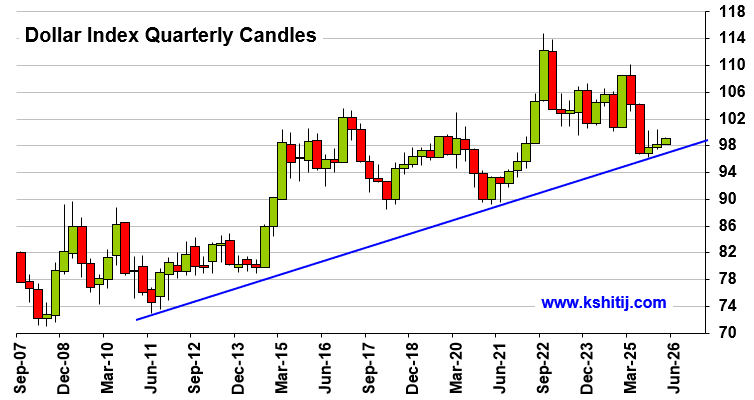
Dollar Index remains strong and is headed towards crucial resistance near 103.8-104, while most other currencies look weak against it. Euro has broken below 1.10 and can test 1.0950. Dollar Yen is firm below 160.50, EURINR is heading towards 103 and can decline further towards 102-101. Aussie is bearish towards 0.67-0.66. Pound has broken below crucial support at 1.32 and can fall towards 1.31-1.30. USDCNY looks stable to bearish below 6.67, whereas USDINR has limited its rise to 94.25 contrary to our expected rise to 94.50 and has slipped below 94. It can test 93.75 or lower while it sustains trade below 94.
Dollar Index (103.64) continues to rise and is headed towards resistance near 103.8-104 while EURUSD (1.0991) has broken below our expected 1.10. Unless an immediate rebound is seen, we may see a test of 1.0950 in the near term.
Dollar-Yen (159.48) has dipped slightly. While below 160.50, a short corrective dip could be seen towards 159-158. EURJPY (175.28) could rebound from anywhere in the 175-172 support region.
EURINR (103.1892) is headed towards 103. A break below this, if seen can make it vulnerable to test 102-101 region.
USDCNY (6.6645) could be ranged to bearish in the near tern below 6.67
Aussie (0.6736) is headed towards 0.67. Thereafter, a break lower, if seen will open lower targets of 0.66.
Pound (1.3179) has broken below the support at 1.32 and could be headed towards 1.31-1.30 in the coming days. Overall view is bearish.
USDINR (93.9120) has limited its rise to 94.25, not testing our expected 94.50 on the upside and declined sharply to close below 94. This has been a larger than expected move yesterday. If the spot sustains below 94-93.80, we may have to allow for a further dip towards 93.50/25. Else an immediate bounce back above 94 is needed for a rebound back towards 94.25/30. We would have to wait for a couple of days to get that directional clarity from current levels.
INTEREST RATES
The US Treasury Yields sustain higher. The oulook remains bullish. The Yields can rise more from here. The German Yields have moved up well in the last couple of days. That keeps intact our overall bullish view. The Yields have potential to rise further. The 10Yr GoI has a resistance coming up. It has to break this resistance to go further higher. Else, a pullback move is possible. We will have to wait and see.
The US 10Yr (5.13%) and 30Yr (5.48%) Yields sustain higher. The bullish view is intact to see 5.2% (10Yr) and 5.6% (30Yr).
The German 10Yr (3.39%) and 30Yr (3.74%) Yields have moved up well in the last couple of days. They have potential to target 3.7% (10Yr) and 4%-4.1% (30Yr on the upside. Immediate support is at 3.355 (10Yr) and 3.7% (30Yr).
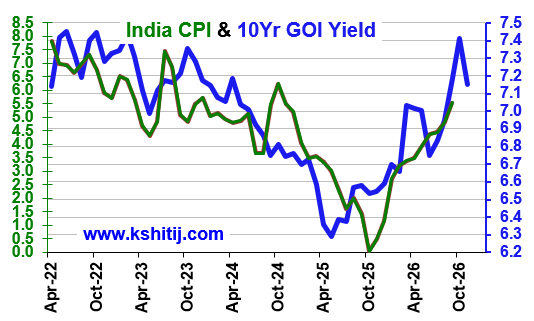
The 10Yr GoI (7.3169%) is holding higher. Resistance is at 7.35% which if broken can take the yield higher to 7.4%. Else a dip to 7.25%-7.2% is possible. We will have to wait and see.
STOCKS
Global equities remain under pressure, with the Dow and DAX weak and downside towards 51,000-50,800 and 26,000. Nifty needs to hold above 25,000 to rise towards 25,500-25,800. Nikkei remains weak below 62,000, with scope to decline towards 57,000. Shanghai remains weak below 3,650, with downside towards 3,550-3,500.
Dow (51608.17, -1.41%) has declined sharply to test the low of 51511 before closing at the current level as expected. A decisive move below 51500 will drag the index further lower towards 51000-50800 in the coming weeks.
DAX (26598.64, -0.57%) has fallen as expected to test the low of 26598 so far before closing. Further decline towards 26000 looks possible in the coming session while it holds below 27000.
Nifty (25291.10, +0.58%) may open flat today and needs to hold above 25000 to rise higher towards 25500-25800 in the coming weeks.
Nikkei (59150.02, -0.85%) remains weak. While below 62000, it stays vulnerable to a decline towards 57000.
Shanghai (3602.57, -0.87%) has tested the low of 3586 before closing. While it stays below 3650, the index remains vulnerable to a further decline towards 3550-3500 in the coming session.
COMMODITIES
Crude oil prices dropped on lower IEA demand forecasts. Brent and WTI remians bearish towards 88–85 and 82–80, respectively. Gold remains at a crossroads, facing either a breakdown below 3850 toward 3800–3700 or a recovery toward 4000. Silver tested 46.46 as expected and can test 45 before a meaningful bounce is seen. Copper broke below 6 to target 5.75–5.50, while Natural Gas remains weak toward 3.0.
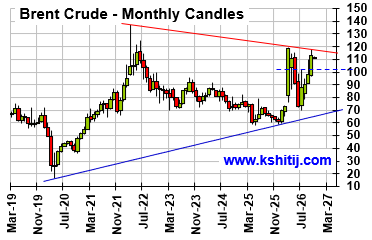
Brent ($91.71) and WTI ($85.12) prices were weighed down on Monday by negative carryover from last Friday, when the International Energy Agency (IEA) cut its 2026 global crude oil demand forecast to 102.29 million bpd, down 90,000 bpd from last month's estimate. A further decline towards 88–85 and 82–80, respectively, remains likely in the near term.
Gold ($3866.70) remains at a crossroads, as mentioned yesterday; it remains to be seen whether it breaks further below 3850 to extend bearish momentum towards 3800–3700, or bounces back towards 4000.
Silver ($47.14) tested 46.46 yesterday in line with our expectations and could decline further towards 45 in the near term before any bounce back is seen.
Copper ($5.9885) has broken below 6 as cautioned yesterday and can now decline further towards 5.75–5.50.
Natural Gas ($3.1080) remains weak, having tested a low of 3.08 yesterday in line with expectations, and could decline further towards 3.0.
DATA TODAY
6:00 11:30 UK Unemp
...Expected 4.7 % ...Previous 4.7 %
13:30 19:00 US Retail Sales (MoM)
...Kshitij Expn. 0.0 % ...Expected 0.2 % ...Previous 0.7 %
14:15 19:45 US Industrial Production
...Kshitij Expn. 0.0 % ...Expected 0.1 % ...Previous 0.7 %
14:15 19:45 US Capacity Utilization
...Kshitij Expn. 76.9 % ...Expected 76.8 % ...Previous 76.9 %
DATA YESTERDAY:-
-------------
JP GDP
...Exxpected 0.1% ...Previous 0.4% ...Actual 00% -
IN WPI
...Expected 12.10%...Previous 11.39 % ...Kshitij Expn.12.04% ...Actual 12.29%
EU Ind Prodn (MoM)
...kshitij Expn -0.3 % ...Previous -0.5 % ...Expected 0.3 % ...Acctual 0.6%
CA Inflation Y/Y
...Previous 3.1 %
CN Retail Sales
....Actual 0.4% ...Expected 0.8 % ... Previous 1.1 %
CN IIP (YoY)
...Actual 4.8% ...Expected 5.3% ...Previous 5.5 -
DISCLAIMER
These views/ forecasts/ suggestions, though proferred with the best of intentions, are based on our reading of the market at the time of writing. They are subject to change without notice.Though the information sources are believed to be reliable, the information is not guaranteed for accuracy. Those acting in the market on the basis of these are themselves responsible for any profits or losses that might occur, without recourse to us. World financial markets, and especially the Foreign Exchange markets, are inherently risky and it is assumed that those who trade these markets are fully aware of the risk of real loss involved.
WARNING !!
Visitors should be aware that Foreign Exchange transactions and trading are or can be subject to laws, rules and regulations of the country in which the entity undertaking the transactions is situated. It is incumbent upon the Visitors to keep themselves informed and abreast of the Laws they are (or would be expected to be) subject to and governed by, and act in accordance thereto.